
Debunking Common Reverse Mortgage Myths: Eric Steenstra Helps Homeowners in Cape Cod, Plymouth, Norfolk, and Bristol Counties Maximize Retirement Potential
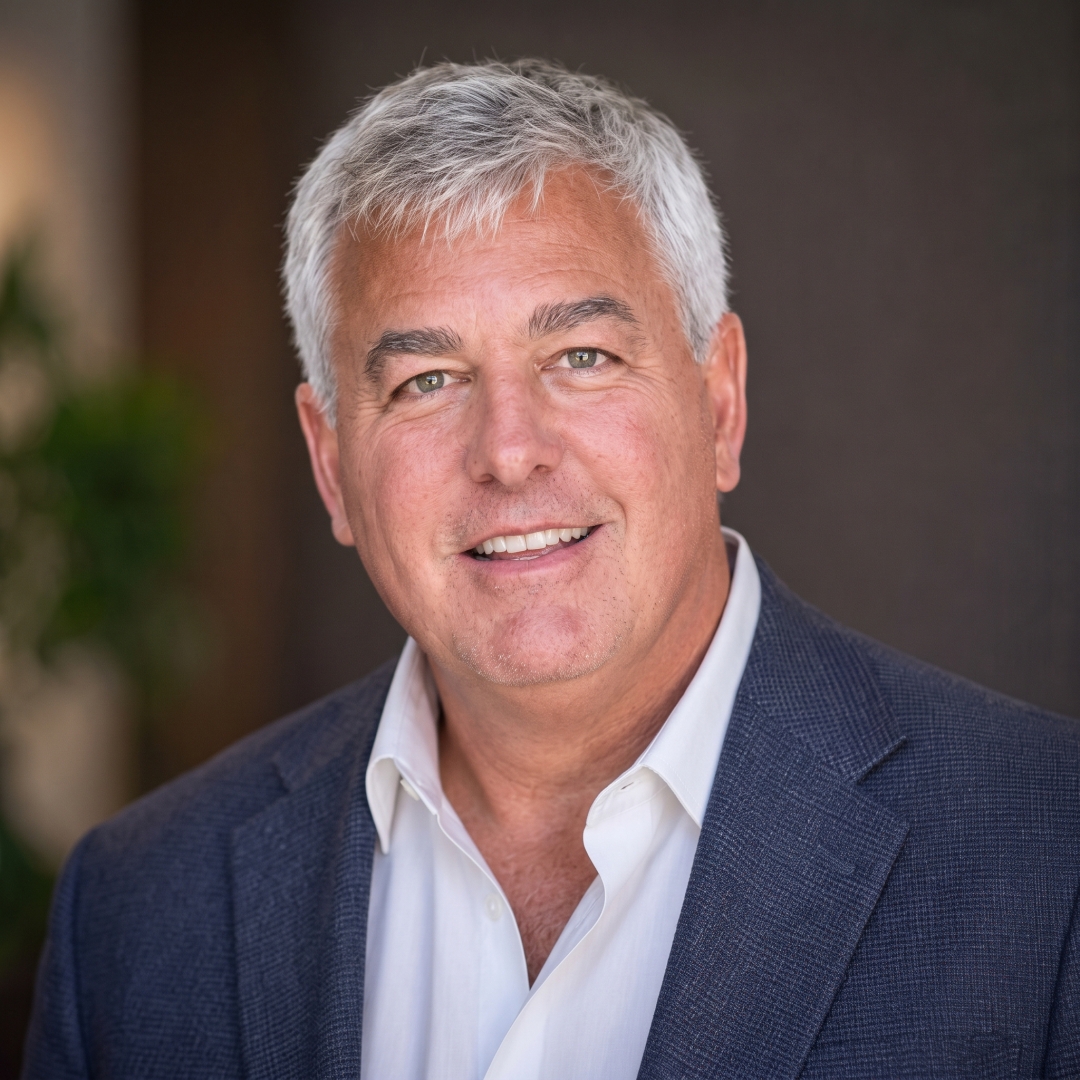
HYANNIS, MA, October 16, 2026 – Many senior homeowners across Massachusetts hold substantial equity in their properties, representing a valuable financial asset that could significantly enhance their retirement years. However, persistent misconceptions about reverse mortgages often prevent these homeowners from exploring a powerful financial tool designed to support their long-term security. Eric Steenstra, a leading mortgage professional and dedicated loan officer Plymouth MA residents trust, is on a mission to clarify these misunderstandings. Serving communities across Cape Cod, Plymouth, Norfolk, and Bristol counties, Steenstra and his team at New American Funding are empowering homeowners with accurate, fact-based information regarding their home equity options.
For years, reverse mortgages have been shrouded in myths that deter homeowners from considering them as a legitimate and beneficial financial option. Especially for residents in high-value real estate markets like Cape Cod and the surrounding coastal and suburban counties, understanding the true nature of a reverse mortgage can be a transformative element of retirement planning. This financial instrument allows older Americans to remain in their homes with greater financial freedom, transforming illiquid home equity into usable, tax-free funds.
“Our primary goal is to provide transparent, factual information so clients can make highly informed decisions tailored to their unique circumstances,” says Eric Steenstra, Branch Manager at New American Funding. “We want to ensure that homeowners in Cape Cod, Plymouth, Norfolk, and Bristol counties understand that a reverse mortgage is not a last resort. Rather, it is a strategic financial planning tool designed to support long-term security, independence, and peace of mind.”
Separating Fact from Fiction: Top Reverse Mortgage Myths Debunked
To help homeowners make educated decisions, Eric Steenstra and his team have identified and debunked the most common myths surrounding reverse mortgages, specifically focusing on the federally insured Home Equity Conversion Mortgage (HECM) program.
-
Myth 1: The Bank Takes Ownership of Your Home.
Fact: This is perhaps the most pervasive falsehood. With a reverse mortgage, you, the homeowner, retain the title and full ownership of your home. It functions similarly to a traditional mortgage, where the lender places a lien on the property, but you remain the absolute owner.
-
Myth 2: Reverse Mortgages Are Only for the Financially Desperate.
Fact: While a reverse mortgage can provide crucial financial relief, it is increasingly being utilized as a proactive, strategic financial planning tool by financially stable retirees. It can provide a tax-free line of credit that grows over time, supplement retirement income, delay Social Security benefits to maximize payouts, or fund necessary home modifications for aging in place.
-
Myth 3: Your Heirs Will Inherit Your Debt.
Fact: Federally insured HECMs are strictly non-recourse loans. This means your heirs will never owe more than the home’s appraised market value at the time of repayment, regardless of the loan balance. If the loan balance exceeds the home’s value, the Federal Housing Administration (FHA) insurance covers the difference. Heirs always have the option to either pay off the loan and keep the home or sell the home to satisfy the loan.
-
Myth 4: You Can Be Forced Out of Your Home.
Fact: As long as you continue to live in your home as your primary residence, pay your property taxes and homeowners insurance, and maintain the property in good condition, you can stay in your home indefinitely. The loan only becomes due when the last surviving borrower permanently moves out or passes away.
-
Myth 5: Monthly Mortgage Payments Are Still Required.
Fact: A defining benefit of a reverse mortgage is that it eliminates the requirement for monthly mortgage payments. This frees up significant cash flow, allowing seniors to better manage daily living expenses. The interest simply accrues over time and is added to the loan balance.
Structured Comparison: Traditional Mortgage vs. Reverse Mortgage
To further clarify the differences, the following table outlines the key distinctions between a traditional mortgage and a reverse mortgage for senior homeowners:
|
Feature |
Traditional Mortgage or Home Equity Loan |
Reverse Mortgage (HECM) |
|---|---|---|
|
Monthly Payments |
Required every month to pay down principal and interest. |
No monthly mortgage payments required. Interest accrues over time. |
|
Age Requirement |
No specific age requirement; based on credit and income. |
At least one borrower must be 62 years of age or older. |
|
Home Ownership |
Borrower retains title and ownership. |
Borrower retains title and ownership. |
|
Loan Repayment |
Repaid monthly over a set term (e.g., 15 or 30 years). |
Repaid when the last borrower leaves the home, sells, or passes away. |
|
Income Requirements |
Strict debt-to-income ratios must be met. |
Financial assessment required to ensure ability to pay taxes and insurance. |
Serving a Broader Community: Beyond Cape Cod
While often recognized for his exceptional work on Cape Cod, Eric Steenstra’s expertise as a premier loan officer extends deeply into Plymouth MA, as well as Norfolk and Bristol counties. The real estate markets in these regions have seen substantial appreciation over the past decade, leaving many long-time homeowners “house rich but cash poor.” By expanding his educational outreach to these specific counties, Steenstra is ensuring that a wider demographic of seniors has access to top-tier financial guidance.
Reverse mortgages are a distinct specialty for Steenstra. He leverages his diverse background as a former Series 7 licensed financial advisor and a software industry consultant to provide comprehensive, holistic financial solutions. This unique perspective allows him to analyze a client’s entire financial picture, ensuring that a reverse mortgage aligns perfectly with their broader retirement objectives.
Furthermore, Steenstra brings a unique level of discipline and commitment to his role. As a former Division 1 athlete and captain of the Penn State University Track and Field team, as well as a professional athlete on the USA Bobsled team, he understands the pursuit of excellence. These qualities translate directly into his role as a producing branch manager, focusing on exceptional service, tailored solutions, and continuous client education.
A Collaborative and Seamless Approach
Working closely with Production Manager Lauren Leduc (NMLS #2069417), the team at New American Funding ensures a seamless, highly responsive process for every single client. Client testimonials consistently highlight the team’s attentiveness, responsiveness, and proactive communication. Whether clients are seeking a reverse mortgage, a conventional loan, veteran loans, no down payment options, or specialized programs for self-employed borrowers, the team provides a partnership approach rather than a transactional one.
“Lauren and Eric are an incredible team and are outstanding to work with,” notes one recent client review. “They are knowledgeable, professional, responsive, and proactive in identifying and resolving issues before they become problems. Their expertise, communication, and commitment to their clients truly set them apart.”
Call to Action: Explore Your Home Equity Options Today
Homeowners in Cape Cod, Plymouth, Norfolk, and Bristol counties who are interested in learning more about reverse mortgages and how they might fit into a comprehensive retirement strategy are highly encouraged to reach out for a personalized consultation. By calling the direct line at 508-685-2716, clients can speak directly with Eric Steenstra and his dedicated team to get their questions answered without any pressure or obligation.
Additionally, clients and partners can look forward to the upcoming launch of teamsteenstra.com. This dedicated online resource is currently in development and will soon be made public pending final approval from Eric and Lauren. Once live, the site will provide even more robust tools, calculators, and educational insights for prospective borrowers navigating the mortgage landscape.
Compliance and Licensing Information
Please Note: Corporate compliance applies to all mortgage lending practices. This press release and the information contained herein are subject to New American Funding’s corporate compliance standards and do not constitute an auto-approval for any loan product. All applications are subject to underwriting approval.
About Eric Steenstra: Eric Steenstra is a Branch Manager and Senior Loan Officer (Individual NMLS: #21548) with New American Funding. He is officially licensed to originate mortgages in Massachusetts (MA), Florida (FL), Rhode Island (RI), New Hampshire (NH), Maine (ME), Pennsylvania (PA), and North Carolina (NC). Recognized for consistently ranking in the top 1 percent of loan officers nationally, Eric is dedicated to delivering the best possible mortgage options for his clients.
About New American Funding: New American Funding (Company NMLS: #6606) is a national mortgage lender and servicer offering a wide array of loan products, including Conventional, FHA, VA, USDA, Jumbo, and Reverse Mortgages. The company is deeply committed to delivering an unparalleled client experience through innovative technology, diverse loan options, and exceptional customer service.
Media Contact Information
Eric Steenstra
Title: Branch Manager / Sr. Loan Officer
Email: teamsteenstra@nafinc.com
Phone: 508-685-2716
Corporate Website: https://www.teamsteenstra.com
Google Business Profile: https://share.google/mUpR3Qg7FoZjNG8cs
Media Contact
Company Name: New American Funding
Contact Person: Eric Steenstra
Email: Send Email
Phone: 5086852716
Address:20 Sea Street Hyannis, MA 02601
City: HYANNIS
State: MA
Country: United States
Website: https://teamsteenstra.com/


